• Link to X
  • Link to Facebook
  • Link to Instagram
  • Link to TikTok
  • Link to Youtube
  • About
    • About Us
      • President
      • Board of Directors
      • Board of Advisors
      • Financials
      • Our Methodology
      • Success Tracker
      • Contact
  • Act Now
    • 30 Ways to Help
      • Email Congress
      • Call Congress
      • Volunteer
      • Courses & Certificates
      • Be a Donor
    • Internships
      • In-Office Internships
      • Remote Internships
    • Legislation
      • Politics 101
  • The Blog
  • The Podcast
  • Magazine
  • Donate
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu

Archive for category: Financial Instruments

Financial Instruments, Global Poverty

How Cash Transfers to Women in India are Changing Lives

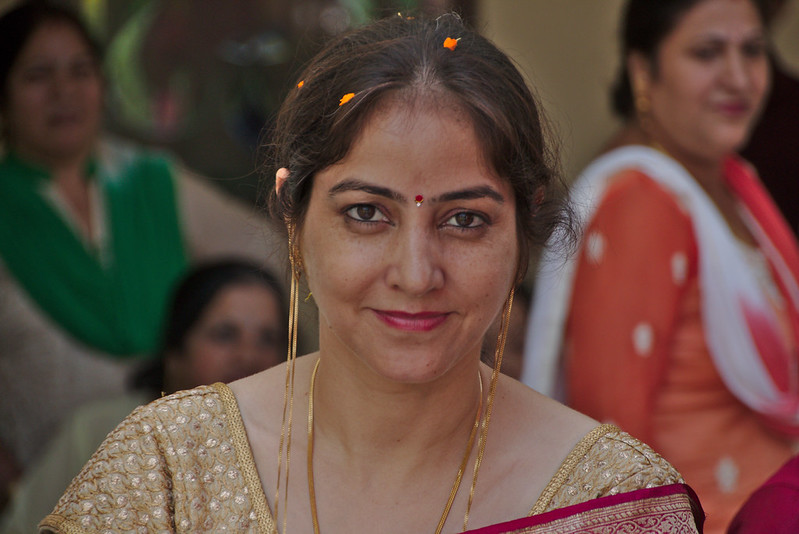
Cash Transfers to Women in IndiaCleaning, tidying, cooking, looking after children and managing family finances are part of the daily lives of many women across India. There are approximately 160 million female homemakers throughout the country, who spend about 297 minutes each day completing domestic work, compared with a significantly lower 31 minutes spent by men. This inequality in time spent on what many scholars argue is “unpaid work” has led the Indian government to introduce a welfare scheme involving cash transfers to women.

Across India, unconditional cash transfers to women are becoming increasingly common, with transfers ranging from 1,000 to 2,500 rupees ($12 to $30) a month. These payments account for roughly 5% to 12% of household income. The money typically goes toward household and family needs such as children’s education, groceries and cooking gas.

Impacts on Women and Households

Research indicates that these small, regular transfers are having a positive effect on the lives of women, with the majority of the money being spent on their own immediate needs and those of their households. Additionally, the transfers have given women a sense of financial security and a newfound confidence, allowed them to become more financially independent from their husbands and reduced marital conflict.

Prabha Kotiwswaran, a professor of law and social justice at King’s College London, told the BBC in December that: “The unconditional cash transfers signal a significant expansion of Indian states’ welfare regimes in favor of women.”

The idea of cash transfers for women was first introduced in 2013 in the state of Goa but only gained momentum before the COVID-19 pandemic in 2020, when the northern state of Assam implemented a scheme for vulnerable women. As of 2025, nearly 15 states run such programs.

Politics and Public Debate

Since then, cash transfers have gained political power, with both government and opposition parties introducing them as a strategy to mobilize female voters. The result of this can be seen in the 2025 Delhi assembly election, where the female voter turnout reached 60.92%, exceeding the male turnout for the first time in the country’s history. Critics have called this “blatant vote-buying,” highlighting how financial support can easily be used as political leverage.

Women can become eligible for this financial support simply due to the fact that they do not have a paying job but instead stay at home, keep households running and bear the burden of unpaid care work. Although the amount received can vary due to several factors — such as age thresholds, income caps and exclusions for families with government employees or owners of large plots of land — the government has not put in place conditions similar to those enforced by other countries with large cash transfer schemes. For example, Bolsa Familia, the world’s largest cash transfer scheme in Brazil, requires school attendance for teenagers, immunization of children and prenatal monitoring for pregnant women, among others.

Limits of Cash Transfers

Although these cash transfers to women in India have allowed steps forward, cash transfers cannot substitute for employment opportunities, with many women stating they would still prefer work that pays and respect that endures. It is important that the fight for women’s rights and equal rights is neither forgotten nor lost, and that unconditional cash transfers are a means of raising awareness of the equality that is yet to be achieved.

As cash transfer programs continue across India, they are providing women with greater financial stability and decision-making power within their households. Together with broader social and economic efforts, these initiatives highlight continued progress toward improving the lives of women and families.

– Jenna O’Flynn

Jenna is based in London, UK and focuses on Politics for The Borgen Project.

Photo: Flickr
February 12, 2026
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Precious Sheidu https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Precious Sheidu2026-02-12 03:00:072026-02-12 00:34:34How Cash Transfers to Women in India are Changing Lives
Financial Instruments, Global Poverty

Kaspi: The Future of Online Banking in Kazakhstan

kaspiFor years, Kazakhstan has been working to enhance its use of technology throughout the Central Asian country. From fully digitizing the process of public services, from school enrollment to the issuing of passports, in the past year, Kazakhstan has been ranked 24th globally in digital development due to its digital progression as a country. Therefore, it comes as no surprise that the country’s leading banking service has been working hard to bring the world of digital payments to life, with a unique twist.
Background

However, this change does not come without a few issues. With the increase in daily technology usage in the country, digital scams have become more common. The Times of Central Asia reports that since July 2024 alone, anti-fraud centers have suspended more than 63,000 suspicious transactions across the country that amounted to over four million dollars. Most of these scams, according to the Times, stem from the use of cell phones. Another large factor in these scams includes the use of SIM cards under false identities. These scams can target anyone, but they have a devastating impact on those who struggle financially or are otherwise vulnerable.

Kaspi

Defined as “the largest consumer-focused ecosystem in Kazakhstan” through its website, Kaspi is much more than a banking platform. Besides allowing its users to pay for utilities or their education with their app, the Central Asian banking platform also has its own marketplace, where users can buy anything from cell phones to stuffed animals through different merchants. Think of the Shop App as Kaspi, but without the banking aspect; with both apps, you can track your purchases, pay for almost anything through installments, and find unique offers on products from merchants.

Unlike the Shop App, Kaspi is allowing its users to pay with a part of their body. When it comes to paying with facial recognition or a fingerprint, like many Apple Pay or Samsung Pay users experience as a way of verifying any day-to-day purchase, Kaspi has launched a new service where customers are able to pay with the palm of their hand. The “Kaspi Alaqan,” service is “easier” than paying with your card, phone or digital wallet, according to the company, particularly because there is no WiFi connection necessary for the payment to go through.

Safety

Kazakhstan’s leading financial tech company promises that this new service is safe, going as far as to say that “palm payment is one of the most secure methods of payment,” referencing the decade-old usage of the technology in Japan, as well as the current developments of it in China and the United States. The company states that due to the unique structure of your palm, it is “virtually impossible” that someone would be able to access this form of payment.

Furthermore, the company reassures that this is a safe practice, as it collects palm’s biometric data, converts it into a digital code, encrypts and then stores it for future use, only accessible within Kaspi. This makes it harder for scammers to steal your information, given that they don’t need your banking password to drain your entire banking balance, but instead, the live palm of your hand, which can only be used to make purchases.

The Future

Kazakhstan’s leading financial services company, Kaspi, has stated that in December, this form of payment is going to become available at ATMs in Almaty, the country’s largest city, before a larger rollout nationwide. On an additional note, Kazakhstan’s government has set a goal of a $450 billion gross domestic product (GDP) by 2029, and digital technologies, such as Kaspi Alaqan, are “central” in reaching this national goal. In order to do this, the government launched the National Artificial Intelligence Platform earlier this year, hosting more than 100 AI agents that expand access to technology. Recently, this technology has become available to start-ups, universities, and research programs.

– Megan Akers

Megan is based in Fredericktown, OH, USA and focuses on Technology and Solutions for The Borgen Project.

Photo: Kalpak Travel

December 26, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Naida Jahic https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Naida Jahic2025-12-26 07:30:302025-12-20 08:13:16Kaspi: The Future of Online Banking in Kazakhstan
Financial Instruments, Global Poverty

Debt Relief in Somalia: Billions for Growth and Development

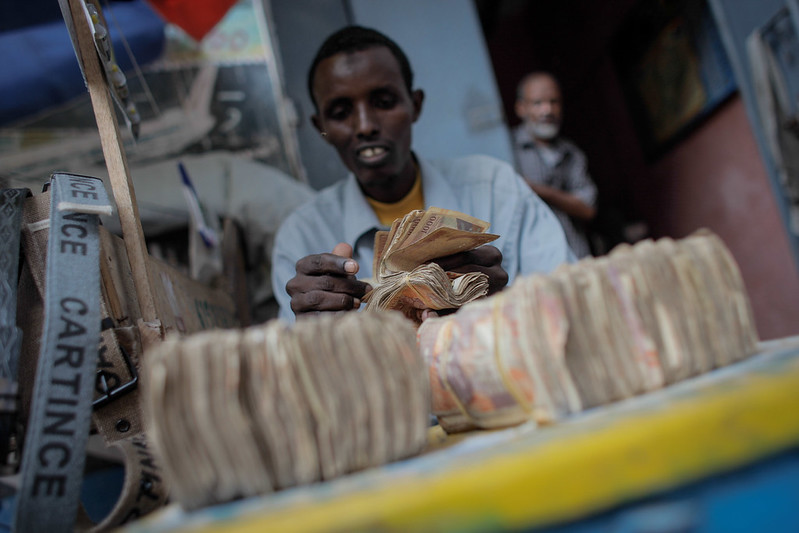
Debt Relief in Somalia Unlocks Billions for Growth and Development On Dec. 3, the African Development Bank Group announced that it approved additional debt relief for Somalia, amounting to $17.68 million and marking another milestone on the path to full debt-free status. The Bank Group’s lead operations adviser for Somalia, Bubacarr Sankareh, said, “Somalia has earned this moment through determination and discipline.”

This milestone represents the convergence of persistent national effort and a strategic international partnership. Through coordinated bilateral and multilateral engagement, Somalia secured debt alleviation, most notably under the Heavily Indebted Poor Countries Initiative, launched in 1996 by the International Monetary Fund and World Bank to provide relief to countries burdened by unsustainable debt, while simultaneously reforming its economy and reconstructing state institutions. These efforts are notable for a country that endured decades of conflict and institutional collapse.

The Weight of Historical Debt

Most of Somalia’s debt accumulated during Siad Barre’s military dictatorship, which collapsed in 1991 and plunged the nation into civil war. These debt levels, coupled with instability, limited investment in health, education and infrastructure. In 1993, Somalia’s Human Development Index stood at 0.221, reflecting the lived consequences of these conditions. The debt crisis also severed Somalia’s engagement with global financial markets, deterring investors, creditors and potential trade partners who might otherwise have contributed to reconstruction efforts.

The Path to Relief

Breaking free from this debt trap required Somalia to meet exacting standards under the HIPC framework, which supported more than 30 heavily indebted nations. Participation required demonstrated implementation of domestic structural reforms. Somalia’s reform package was comprehensive and prioritized rebuilding state institutions and restoring public finances while incentivizing a competitive private sector.

With more than two-thirds of the population living on less than $2.15 a day, the government launched Baxaano, the nation’s first social safety net program. This initiative provided nutrition-linked cash transfers and emergency assistance to 3.7 million people. These reforms enabled Somalia to complete the HIPC process in December 2023, securing $4.5 billion in debt cancellation.

In March 2024, nearly all debt owed to members of the Paris Club, a group of wealthy creditor nations, was canceled. This cancellation is set to be finalized by the end of December 2025. In June, a further relief agreement with the OPEC Fund for International Development cleared $36 million. In November 2024, the United States, Somalia’s largest bilateral lender, which held approximately 20% of total external debt in 2018, forgave $1.1 billion in loans.

The cumulative impact of these measures reduced external debt from 64% of GDP in 2018 to 4.9% in 2025. This fiscal transformation occurred alongside measurable poverty reduction and strengthened institutional capacity.

Unlocking Resources for Development

Debt relief in Somalia means resources previously used for debt servicing can now fund social programs and infrastructure, allowing the government to better implement its National Transformation Plan. Sankareh stated that alleviation “opens the door for stronger institutions, better services and brighter prospects for Somali citizens, with impacts felt in classrooms, clinics, farms and markets.” Improvements have already been noted in health care, education and infrastructure.

Restored creditworthiness may reverse the investment drought that persisted for decades, particularly following Somalia’s recent integration into the East African Community, which provides access to regional markets of more than 300 million people. Somalia’s coastline positions it to develop blue economy sectors ranging from fisheries and port infrastructure to maritime transport.

Somalia stands at a turning point, with the potential to follow the paths of Uganda and Rwanda, where foreign investment flows and capital reforms following conflict and debt relief supported sustained investment in public infrastructure and transformative sectors.

Debt forgiveness provides fiscal breathing room, but sustaining momentum requires transitioning from grant dependence toward broader financial market participation. This includes developing sovereign bond capacity, expanding equity markets and deepening microfinance penetration. The International Monetary Fund identifies strengthened financial oversight and regulatory reform, including modernized fiscal codes and streamlined customs, as essential for attracting sustained investment. An effective tax system also remains necessary for long-term domestic resource mobilization.

A Model for Post-Conflict Recovery

Somalia’s debt relief trajectory offers insights for countries facing legacies of conflict and underdevelopment. It demonstrates that fragile states can rebuild credibility through governance reforms and transparent financial management. While international cooperation proved essential, progress ultimately depended on Somalia’s ownership of the reform process.

As Somalia’s deputy prime minister, Salah Jama, told the World Bank’s Fragility Forum, “We are out of failure … and working very hard to get out of fragility,” a statement that reflects both progress made and the vigilance still required. Debt relief in Somalia demonstrates that countries committed to reform, supported by coordinated international engagement, can overcome deeply entrenched challenges.

– Caroline Sheehan

Caroline is based in Edinburgh, UK and focuses on Good News, Politics for The Borgen Project.

Photo: Flickr

December 18, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Precious Sheidu https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Precious Sheidu2025-12-18 07:30:132025-12-18 00:16:24Debt Relief in Somalia: Billions for Growth and Development
Financial Instruments, Global Poverty, Government

G2Px: Digitizing Government-to-Person Payments

G2PxAround the world, low-income communities often face two overlapping challenges: limited access to government assistance and barriers to digital and financial services. At the intersection of these issues is a growing solution: digitizing government-to-person (G2P) payments.

Closing a Digital and Financial Divide

Government payments for retirement, disability, unemployment and basic needs are critical for many households and individuals. However, accessing these benefits is not always straightforward. Payments were traditionally made in cash and required in-person collection, which creates barriers for people living in remote areas, those with limited mobility or individuals who cannot afford to take time off work.

“When there is a payment, we spend the whole day at the town hall, we leave in the morning from our village to come back in the evening and that is a difficulty,” said one Malian cash recipient in a World Bank report. By shifting government-to-person payments to digital platforms, recipients gain incentives to access financial services. This helps close the digital divide, promotes digital literacy and offers more secure financial access.

A Path to Financial Inclusion

Digital G2P payments can serve as a first step toward broader financial inclusion. For many recipients, especially in low-income or rural areas, receiving government payments through a bank or mobile account is their first interaction with the formal financial system.

According to the World Bank, 865 million account owners in developing countries—including 423 million women—opened their first financial institution account to receive government payments. This initial connection can lead to increased use of financial services such as saving, borrowing or making digital transactions. The impact is particularly significant for women and young people, who often face additional barriers to financial access.

The G2Px Initiative: Progress and Empowerment

Despite progress in digital government-to-person payments, the digital and financial inclusion gap remains, with 1.4 billion adults still unbanked worldwide. To help close this gap, the World Bank Group created the G2Px initiative. In partnership with the Bill & Melinda Gates Foundation and Norad, the initiative supports governments in improving G2P systems through policy development, design improvements and digital and financial literacy programs.

In a 2023 report, the World Bank Group highlighted how G2Px supported data collection that helps modernize G2P payments with recipients at the center. The report documented good practices that countries can adopt, and many nations have since joined the conversation. Sierra Leone launched its first account-based social assistance payments, while Yemen completed a study to inform mobile money pilots in eight districts, with 18,000 recipients already registered to opt in.

Technical assistance from the initiative also supported policies that promote inclusion. Jordan’s National Aid Fund revised program design to enable government-to-person payments to women instead of only heads of households.

This empowerment is one of the key benefits of digitizing G2P payments. Access to digital payments can strengthen women’s privacy, financial autonomy, decision-making and labor force participation. Payments also increase opportunities to access financial services such as savings, credit, remittances and insurance. When both men and women in a household can access payments, women’s participation in household decision-making increases.

To support women’s economic empowerment, a World Bank partnership in Liberia developed a simple financial planning intervention to help couples plan the use of their G2P payment before receiving it. This approach not only increased women’s inclusion but also improved the household’s overall financial condition.

Moving Forward

Digitizing government payments is helping millions of people access assistance more efficiently and securely. With continued investment in inclusive design and digital literacy, this approach has the potential to reach more underserved communities and contribute to long-term poverty reduction.

– Jannah Khalil

Jannah is based in Sacramento, CA, USA and focuses on Good News and Global Health for The Borgen Project.

Photo: Flickr

November 29, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Precious Sheidu https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Precious Sheidu2025-11-29 01:30:572025-11-28 10:37:36G2Px: Digitizing Government-to-Person Payments
Financial Instruments, Global Poverty

Kotani Pay: Can Blockchain Reduce Poverty?

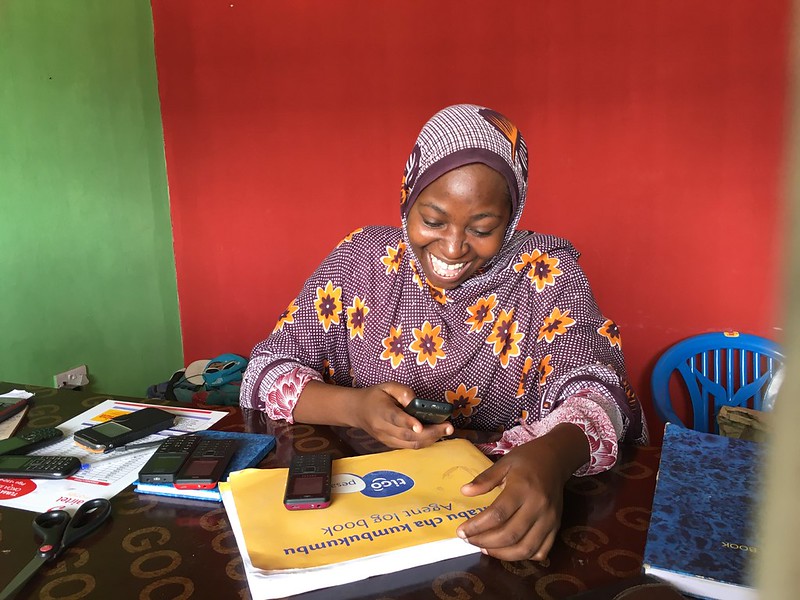
Kotani PayIn many developing countries, people lack access to financial instruments such as mobile banking. These services often require smartphones and the internet, creating a major barrier for low-income communities and limiting participation in the global economy. As a result, cash is often the only option, leaving individuals without secure ways to save or transfer money. According to the World Bank, 51% of adults in sub-Saharan Africa are without a bank account.

Financial inclusion is crucial for poverty alleviation. Services such as blockchain can expand access to financial systems, reduce transaction costs, and provide security and transparency. Innovative platforms such as Kotani Pay, a blockchain-based system that does not require the internet, are bridging the gaps in Africa.

What is Blockchain?

Blockchain is a decentralized and tamper-proof digital ledger recording transactions across a distributed network. It is a technology which provides security and transparency without the need of traditional intermediaries such as banks. This allows faster, cheaper and more efficient transactions without people needing a traditional bank account.

Key benefits of blockchain include:

  • Security and transparency: Transactions are recorded immutably and can be verified without a central authority
  • Lower costs: Reduces fees compared to traditional banking or remittance services
  • Global access: Enables cross-border payments and international trade even for underserved populations

By reducing these barriers, blockchain can reduce poverty by giving individuals a tool to save, invest, and receive financial support.

Blockchain and Financial Inclusion

Many financial systems are designed assuming users have smartphones, internet access, and identification documents. Throughout Africa, however, millions of people lack these resources, especially in rural areas. Blockchain platforms that adapt to local realities, such as supporting Unstructured Supplementary Service Data (USSD) transactions or mobile-money-compatible wallets, can extend financial services to previously excluded populations.

Stablecoins, digital currencies pegged to traditional assets like the U.S. dollar, also reduce the risk of currency fluctuations for low-income individuals, making savings and transfers more predictable. By providing low-cost, accessible financial services, blockchain directly contributes to poverty reduction.

What is Kotani Pay?

Kotani Pay is a Kenyan startup which brings financial services to those without internet or traditional bank accounts. Kotani Pay is a service that lets users access blockchain and cryptocurrencies via USSD. Using USSD codes, Kotani Pay enables users to:

  • Send and receive money securely
  • Convert digital assets into local currency
  • Participate in programs such as Universal Basic Income (UBI)

“We built Kotani Pay to bring financial instruments and services to those who do not have access to the Internet or have the capital and credit standing to open a bank account, thus increasing financial freedom.”

How It Works

Users can dial a short code on their phone to access a menu where they can convert crypto to fiat, and vice versa. This simplified process enables users to transfer funds between their blockchain and wallet. Kotani Pay uses a stablecoin, Celo Dollars (cUSD), which is pegged to the U.S. dollar, protecting users from the otherwise common volatility of cryptocurrencies.

Because Kotani Pay focuses on helping underserved communities, they correct the typically high fees for cross-border transactions, increasing financial stability for those sending money abroad to their family, or those crossing borders fleeing for safety.

Since its launch, Kotani Pay has reached more than 15,000 beneficiaries, including refugees, gig workers, and rural farmers, UNICEF reports. By providing predictable financial support and easy access to transactions, Kotani Pay helps people start small businesses, save safely, and engage with the economy.

The Future

In the fight for financial inclusion, blockchain could reduce poverty more effectively than conventional banking reforms. Blockchain is not the only and sole solution, but it can play a key role in reducing financial exclusion. If Kotani Pay proves successful, the opportunity for scalability is huge. And with that, reduce global poverty. Its main challenge however, is regulation and legislation. With a mission of serving the entire continent, meeting each countries’ regulatory requirements has slowed its growth. But it has not halted its mission.

Whether blockchain reduces poverty is down to how effectively governments, innovators, and communities can implement inclusive and affordable solutions. By providing secure, low-cost, and accessible financial tools, blockchain platforms like Kotani Pay are helping African communities participate in the global economy.

– Ashley Pfeifer

Ashley is based in London, UK and focuses on Business and NGood News for The Borgen Project.

Photo: Flickr

November 10, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Naida Jahic https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Naida Jahic2025-11-10 03:00:502025-11-09 23:38:39Kotani Pay: Can Blockchain Reduce Poverty?
Developing Countries, Financial Instruments, Global Poverty

The Impacts of Savings Groups in Malawi

Savings Groups in MalawiMalawi is a low-income country in East Africa. It is one of the 10th most impoverished countries in the world in terms of GDP per capita and more than 50% of its population officially lives below the national poverty line. Many Malawians do not have access to formal banking due to a lack of banking infrastructure or a fundamental lack of personal wealth. Savings groups in Malawi have primarily replaced banking and have the potential to eradicate poverty in this country.

What Are Savings Groups?

Savings groups are small community-based groups, between 15 and 25 people, who each place an amount of money into a central holding, allowing them to save money on a small and relatively stable basis. They provide a transparent and democratic form of microfinance, serving as an alternative where formal banking is unavailable. Benefits include:

  • Loans become available to more impoverished people who cannot access them from formal institutions.
  • Young people can learn how to save, borrow and invest money in a safe environment, rather than going into adult finance without experience.
  • Women, generally one of the most vulnerable groups economically, can gain independence through savings groups.
  • Essential local infrastructure can be sustainably built and maintained.

Crucially, Plan International emphasizes that savings groups are vital in reaching the first Sustainable Development Goal (SDG). The SDGs are a set of international goals agreed upon by the U.N. and targeted for completion by 2030, with the first goal focused on eradicating global poverty in all its forms.

Impacts of VSLAs in Malawi

Village Savings and Loans Associations (VSLAs) are a version of savings groups in Malawi, organized at the village level rather than within smaller groups. They are widespread throughout the country. Impacts include:

  • Savings: Villages working under VSLAs have reported a 34% increase in savings over the last 1.5 to 3 years compared to villages without them.
  • Loans & Credit: Households that are part of a VSLA have increased access to credit and loans. In VSLA areas, the borrowing costs of people taking loans have fallen by 20%.
  • Businesses: VSLAs have correlated with a rise in the number of businesses and profits in Malawi, but household incomes have not yet changed. Although income rises with profits, the effect can be expected to be staggered. Businesses cannot realistically increase incomes until their profit gains prove to be sustainable rather than a one-off.
  • Food Security: Although savings groups in Malawi have not yet had a significant impact on food security, according to Innovations for Poverty Action (IPA), they have helped mitigate the negative effects of droughts. On average, VSLAs have also increased food consumption by one meal per week, showing gradual improvements.
  • Women: VSLAs have had a clear positive impact on women. Malawian women in savings groups report being more empowered, with greater ability to make decisions for themselves and their households.

Malawi is also pursuing digital means for its financial future. According to IPA, the main focus currently is on digitizing records and monitoring how it improves access to finance across the country.

How Effective Are Savings Groups in Malawi?

The IPA report shows that saving groups have been incredibly influential in Malawi. They have provided a vehicle through which the Malawian people can bring themselves up financially. Women have significantly benefited, able to become increasingly economically and socially independent. While there is still a long way to go in eradicating poverty in countries like Malawi, saving groups have proven to be a reliable solution in many aspects and will help push the world toward reaching the primary SDG by 2030.

– Oliver Evans

Oliver is based in Devon, UK and focuses on Good News for The Borgen Project.

Photo: Flickr

October 10, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Lynsey 2 https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Lynsey 22025-10-10 07:30:242025-10-10 02:20:07The Impacts of Savings Groups in Malawi
Aid, Financial Instruments, Global Poverty

GiveDirectly’s Cash Transfer Scheme

GiveDirectly’s Cash Transfer Pilot SchemeGiveDirectly is a nonprofit organization that has adapted an unconventional approach to poverty alleviation. Founded in 2009, the organization has been sending direct cash transfers to people living in extreme poverty, distributing more than $900 million to around 1.7 million recipients across Bangladesh, Kenya, the DRC, Liberia, Malawi, Mozambique, Rwanda and the United States (U.S.). Unlike traditional aid models, which often predetermine what impoverished communities “need”, GiveDirectly’s cash transfer scheme prioritizes autonomy. It ensures that the recipients themselves decide what to spend the money on, recognizing that the poor can identify their own needs. 

How it Works

GiveDirectly primarily operates through mobile money platforms, sending recipients one lump sum through a single online transfer. How to spend the money is entirely up to the individual’s discretion, but typically people choose to spend it on health care, education and housing improvements. Typically, the organization targets whole villages at a time. All households eligible within a given community receive the same transfer, which greatly minimises tension but maximises collective benefit.

Cash transfers remain an uncommon form of aid, but there is strong evidence to indicate the effectiveness of this method, especially when it comes to health. 

Impacts on Infant Mortality

In rural Kenya, GiveDirectly’s cash transfer pilot scheme, in partnership with Lwala Community Alliance, led to measurable improvements in infant mortality rates. Infant mortality rates in rural Kenya remain six times higher than in the U.S., largely due to barriers in accessing prenatal care, safe delivery environments and adequate nutrition. 

According to reports, 1,500 expectant mothers received a single cash transfer, alongside community-based health support. Most women used this money to fund transportation to and from clinics, prenatal visits, food and to purchase items for their newborns. The outcome of the scheme was notable. Infant mortality decreased by 48%, underscoring how financial empowerment, even though only a moderate sum, can enable mothers to secure essential resources that allow for safer pregnancies and healthier babies.

Impacts on Illness

Beyond maternal health, direct cash transfers have also been of significant benefit to individuals living with or at risk of infectious disease, such as tuberculosis (TB). Although TB is both preventable and curable, poverty remains a barrier as many of the poorest populations live in overcrowded conditions, with poor ventilation. Cash transfers enable households to invest in conditions that reduce vulnerability to infection.

Recipients can afford cleaner and less crowded housing, purchase more nutritious food to strengthen immunity access medical treatment if needed. For those already infected, transfers can also provide the financial security necessary to take time off work and focus on rest and completion of treatment. All of these factors remain essential for the prevention of transmission, crucial for bringing rates of disease down.

Evidence from Brazil illustrates this impact further. A national cash transfer programme led to a 50% reduction in TB cases, strongly suggesting that financial assistance plays a significant role in tackling the disease. These findings reinforce the conclusion that cash transfers are an effective tool in increasing the health of the poor, where money remains a key barrier.

A Call for Cash Transfers

GiveDirectly’s positive findings highlight the positive potential of cash transfers within the humanitarian aid sector. Through shifting the decision-making power into the hands of the recipients, these programs have produced measurable improvements in health and well-being. Crucially, however, they affirm the agency and autonomy of individuals living in poverty, challenging the narrative that the poor are passive or incapable of making effective choices for themselves.

– Niamh Trinder

Niamh is based in Leicester, UK and focuses on Global Health for The Borgen Project.

Photo: Flickr

October 9, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Precious Sheidu https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Precious Sheidu2025-10-09 03:00:392025-10-09 02:17:48GiveDirectly’s Cash Transfer Scheme
Development, Financial Instruments, Global Poverty

Financing the Future: Samurai Bonds Helping Kenya Grow

Samurai bondsOn August 21, 2025, Kenya secured 25 billion yen (about $169 million) through Japan’s Samurai bond market, a yen-denominated debt instrument backed by Nippon Export and Investment Insurance. The deal is aimed at strengthening Kenya’s vehicle assembly industry and addressing inefficiencies in the energy grid, where transmission losses currently consume nearly a quarter of national output. This marks the first time Kenya has tapped into Samurai financing.

It underscored its efforts to diversify funding sources and pursue more cost-effective borrowing options to finance the future and help Kenya grow. Kenya’s gross public debt has climbed steadily in recent years, from 45.7% of gross domestic product (GDP) in 2015 to 67.8% in 2021. Infrastructure projects and reliance on Eurobonds and bilateral loans drive this. This makes the move toward Samurai financing particularly significant as part of a broader debt diversification strategy.

Why Samurai Bonds Matter

Samurai bonds are yen-denominated loans issued in Japan by foreign entities. For developing countries like Kenya, they represent a critical opportunity to access Japanese capital markets and secure funds at lower interest rates than many dollar-denominated loans. With global debt burdens rising, innovative tools like Samurai bonds provide nations with greater financial flexibility and protection from volatile Western credit markets.

Kenya’s choice to issue Samurai bonds reflects a broader global trend. Countries such as Indonesia and the Philippines have also experimented with similar instruments, demonstrating their usefulness as a way to diversify financing while strengthening international ties. Economists believe these types of bonds, along with Panda bonds in China and sustainability-linked bonds, will become increasingly important.

They help nations manage debt while also seeking funds for sustainable development. As of the most recent analysis, 43% of Kenya’s external debt is multilateral, 31% bilateral and 27% commercial, which are mainly Eurobonds. Samurai bonds provide a way to rebalance this mix and reduce exposure to high-cost commercial borrowing.

Direct Benefits for Kenya

The immediate benefits of Kenya’s Samurai bond financing are of great importance for financing the future of Kenya. First, the funding will support job creation in the country’s growing vehicle assembly plants, part of its broader plan to become a regional manufacturing hub. Second, by modernizing energy infrastructure, the financing will help reduce electricity transmission losses, improving grid reliability for both households and businesses.

This will cut costs, boost productivity and increase competitiveness for local industries. Additionally, tapping into new markets signals investor confidence in Kenya’s long-term prospects. This may encourage future international investment, making it easier for Kenya to access capital at favorable rates.

By diversifying its funding sources, Kenya can avoid over-reliance on a single market or currency, reducing vulnerability to global economic shocks. The Debt Sustainability Analysis has noted that Kenya is vulnerable to external “market financing shocks” as Eurobond markets tighten. This risk has grown, especially following the Russia-Ukraine conflict and global monetary tightening.

A Solution-Focused Shift

Beyond its immediate economic benefits, the Samurai bond deal highlights a solution-oriented approach to Kenya’s development challenges. Traditional loans have often come with high interest rates, rigid repayment terms or political conditions. By pursuing Samurai bonds, Kenya is demonstrating how developing countries can use innovative financial tools to secure resources that are both affordable and aligned with their development needs.

This move also shows the immediate effect of global partnerships in supporting Kenya’s growth. For Kenya, the deal is not only about managing debt, it is about investing strategically in sectors that will generate long-term returns. By strengthening vehicle assembly and energy, the government is targeting industries with strong multiplier effects.

New jobs, better infrastructure and increased investor confidence all feed into broader economic growth to finance the future of the country. Other developing nations may see this as a model worth replicating, signaling a shift toward creative financing solutions that link global capital to local development goals.

Looking Ahead

The full impact of the Samurai bond deal will take time to measure. However, it already represents an important milestone in Kenya’s financial strategy. By turning to innovative financing mechanisms, the country is showing how global partnerships can unlock resources that directly improve people’s lives.

For citizens, the results of global partnerships could include more reliable electricity, new employment opportunities in manufacturing and greater stability in the economy. For the international community, the deal highlights the importance of offering developing nations access to affordable financing tools that allow them to chart their own paths toward sustainable growth.

Kenya’s foray into Samurai bonds is more than just a loan. It is a reminder that creative financial solutions can drive development, reduce poverty and build resilience in a rapidly changing world.

– Nilay Ersoy

Nilay is based in Cambridge, MA, USA and focuses on Business and Technology for The Borgen Project.

Photo: Pxhere

October 8, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Lynsey 2 https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Lynsey 22025-10-08 07:30:532025-10-07 23:57:47Financing the Future: Samurai Bonds Helping Kenya Grow
Financial Instruments, Global Poverty, Women's Empowerment

Women’s Economic Empowerment in Southeast Asia

Women’s Economic Empowerment in Southeast AsiaAcross rural areas of Southeast Asia, self-managed rotating savings and credit associations (ROSCAs) are transforming the economic landscape for women in Vietnam, Cambodia and Myanmar. These community savings and loan groups, built on mutual trust and cooperation, enable women who often lack access to formal banking systems to pool resources, gain capital and invest in small businesses. The ripple effects on household poverty reduction, social capital formation and rural economic diversification are profound, providing a grassroots model for women’s empowerment and inclusive development.

Women’s Economic Empowerment in Southeast Asia

ROSCAs are informal financial groups where members regularly contribute a fixed amount of money into a common fund. This fund is then rotated among members, granting each person access to a lump sum during their turn. Unlike traditional banks, these groups rely on social trust rather than collateral or credit scores, making them especially accessible for women in rural communities where formal financial institutions often exclude them. 

In Vietnam’s Mekong Delta, for example, women farmers participate in ROSCAs to finance agricultural inputs or start small trade ventures. In Cambodia’s Kampong Cham province, these groups help women fund home-based businesses such as weaving or food production. Myanmar’s Chin State has seen women use ROSCA funds to diversify income by investing in poultry or tailoring.

Impact on Poverty and Social Capital

The benefits extend beyond just access to capital. By participating in ROSCAs, women build networks of mutual support and accountability that foster social cohesion. This social capital can be as valuable as the financial resources, encouraging collective problem-solving and resilience in the face of economic shocks.

Studies from the region indicate that households involved in community savings groups experience greater financial stability and reduced vulnerability to poverty. The ability to invest in income-generating activities directly improves livelihoods, while the collaborative nature of these groups enhances women’s confidence and decision-making power within their families and communities.

Driving Rural Economic Diversification

ROSCAs also contribute to broader rural economic diversification. By enabling women to access credit and manage savings, these groups help shift economies away from single-commodity dependence toward a wider variety of small-scale enterprises. This diversification is critical in mitigating risks associated with agricultural price volatility and climate change impacts.

In Cambodia, some ROSCAs have expanded to include group lending and microinsurance schemes. This allows members to pool risks and protect against crop failure or health emergencies. Such innovations demonstrate the potential for ROSCAs to evolve into more complex financial ecosystems tailored to local needs.

Best Practices and Policy Recommendations

Policymakers and development agencies can strengthen the impact of ROSCAs by considering the following:

  • Capacity Building. Provide training on financial literacy and group management to strengthen sustainability.
  • Legal Recognition. Create supportive regulatory frameworks that recognize and protect informal savings groups.
  • Linkages with Formal Finance. Facilitate partnerships between ROSCAs and microfinance institutions or banks to expand access to credit.
  • Inclusive Participation. Promote gender equity and inclusion of marginalized women to ensure broad community benefits.

Governments in Vietnam, Cambodia and Myanmar are increasingly recognizing the importance of grassroots financial mechanisms. Integrating ROSCAs into national poverty alleviation strategies could unlock significant progress toward economic empowerment and poverty reduction.

Looking Ahead

Community savings and loan groups exemplify how local solutions can address systemic barriers and advance women’s economic empowerment in Southeast Asia. By harnessing the power of collective action and social trust, ROSCAs offer a scalable, culturally appropriate path toward financial inclusion. Supporting these groups through policy, capacity building and access to formal financial systems will be vital to sustaining their impact. In a region where millions of women remain financially excluded, grassroots savings associations are not just a means of survival; they are engines of empowerment, transforming lives and communities one cycle at a time.

– De’Marlo Gray

De’Marlo is based in Long Beach, CA, USA and focuses on Business and Technology for The Borgen Project.

Photo: Unsplash

October 7, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Precious Sheidu https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Precious Sheidu2025-10-07 03:00:042025-10-07 01:50:56Women’s Economic Empowerment in Southeast Asia
Financial Instruments, Foreign Relations, Global Poverty

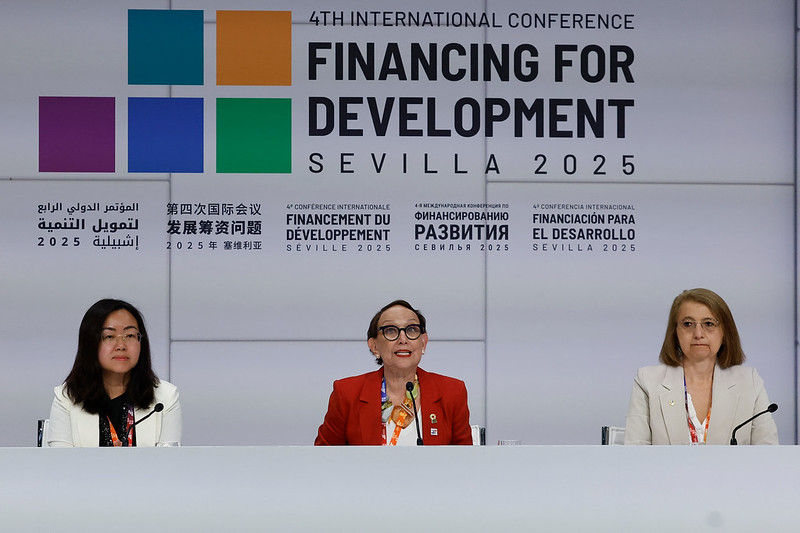
The Seville Commitment: Goals, Challenges and the Future

The 2025 Seville Commitment: Goals, Challenges and Future ConsiderationsThe Seville Commitment is the outcome document of the Fourth International Conference on Financing for Development, held on June 30, 2025, in Seville, Spain. This agreement aims to close the annual $4 trillion gap required to achieve the Sustainable Development Goals (SDGs) by 20230 by mobilizing sufficient financial resources through boosting investments, addressing debt challenges and creating a fairer financial system.

The Background

In 2000, leaders endorsed the Millennium Declaration, which focused on poverty reduction and development as major priorities. They highlighted the challenges developing countries faced in securing sufficient financial resources. In response, they called for a high-level conference to tackle this issue. In 2002, the First International Conference on Financing for Development took place in Monterrey, Mexico. Leaders adopted eight Millennium Development Goals, emphasizing the imperative need for mobilizing financial resources to eradicate poverty and improve living conditions.

In 2008, the second conference held in Doha, Qatar. Leaders adopted an expanded list that includes boosting foreign investment, increasing international cooperation and providing developing nations with debt relief. In 2015, the third conference took place in Addis Ababa, Ethiopia. Leaders produced the Addis Ababa Action Agenda, a new global roadmap for financing development. This new global framework includes protecting the environment, promoting peaceful societies, employment, public services, hunger, sustainable industrialization and infrastructure. In this event, leaders pointed out the gap in financing required to fulfill the development goals. After that, the United Nations (U.N.) substituted the eight Millennium Development Goals with a more demanding 17 SDGs. 

In 2025, the fourth conference was held in Seville, Spain. Leaders discussed the issues for financing development that emerge in a challenging time as countries face increasing debt levels, ongoing conflicts and a decelerating economy. In response, they adopted the Seville Commitment that focuses on solutions to bridge the annual $4 trillion gap in financing development and 130 initiatives were introduced by a coalition of countries, international organizations and other partners.

The Seville Commitment Goals

The Seville Commitment aims to bridge the annual $4 trillion gap required to achieve the SDGs through several actions, including:

  • Increasing the minimum tax revenues to at least 15% of Gross Domestic Product (GDP)
  • Tripling the lending capacity of the multilateral development banks. 
  • Overhauling corporate governance, which includes transparency in how corporations manage funds and measure impact.
  • Addressing the debt challenges by establishing a UN-led group to set guiding principles for lending and borrowing, promoting state-contingent clauses and creating a global debt data registry
  • Creating a fairer financial system by strengthening developing nations’ voices in international financial institutions, such as the International Monetary Fund

Ongoing Challenges

Despite the international cooperation in financing global development, challenges persist. The challenges are as follows: 

  • Cutting the official development assistance by many donors, including Germany, Italy and France, to pay for other priorities such as defense spending 
  • The absence of the U.S, a leader of international development throughout history, at the fourth conference and the termination of many of its foreign assistance programs.
  • Lack of monitoring and accountability systems in markets

Looking Ahead

Reductions in official foreign assistance remain a concern, as they widen the financing gap and slow progress on development efforts. Nonetheless, the Seville Commitment is a major milestone that illustrates the significance of global cooperation in fulfilling the global development goals.

– Eiman Elsawy

Eiman is based in Kirkland, WA, USA and focuses on Business and Politics for The Borgen Project.

Photo: Flickr

September 7, 2025
https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg 0 0 Precious Sheidu https://borgenproject.org/wp-content/uploads/borgen-project-logo.svg Precious Sheidu2025-09-07 01:30:212025-09-07 01:09:31The Seville Commitment: Goals, Challenges and the Future
Page 2 of 3123

Get Smarter

  • Global Poverty 101
  • Global Poverty… The Good News
  • Global Poverty & U.S. Jobs
  • Global Poverty and National Security
  • Innovative Solutions to Poverty
  • Global Poverty & Aid FAQ’s
Search Search

Take Action

  • Call Congress
  • Email Congress
  • Donate
  • 30 Ways to Help
  • Volunteer Ops
  • Internships
  • Courses & Certificates
  • The Podcast
Borgen Project

“The Borgen Project is an incredible nonprofit organization that is addressing poverty and hunger and working towards ending them.”

-The Huffington Post

Inside The Borgen Project

  • Contact
  • About
  • Financials
  • President
  • Board of Directors
  • Board of Advisors

International Links

  • UK Email Parliament
  • UK Donate
  • Canada Email Parliament

Get Smarter

  • Global Poverty 101
  • Global Poverty… The Good News
  • Global Poverty & U.S. Jobs
  • Global Poverty and National Security
  • Innovative Solutions to Poverty
  • Global Poverty & Aid FAQ’s

Ways to Help

  • Call Congress
  • Email Congress
  • Donate
  • 30 Ways to Help
  • Volunteer Ops
  • Internships
  • Courses & Certificates
  • The Podcast
Scroll to top Scroll to top Scroll to top